
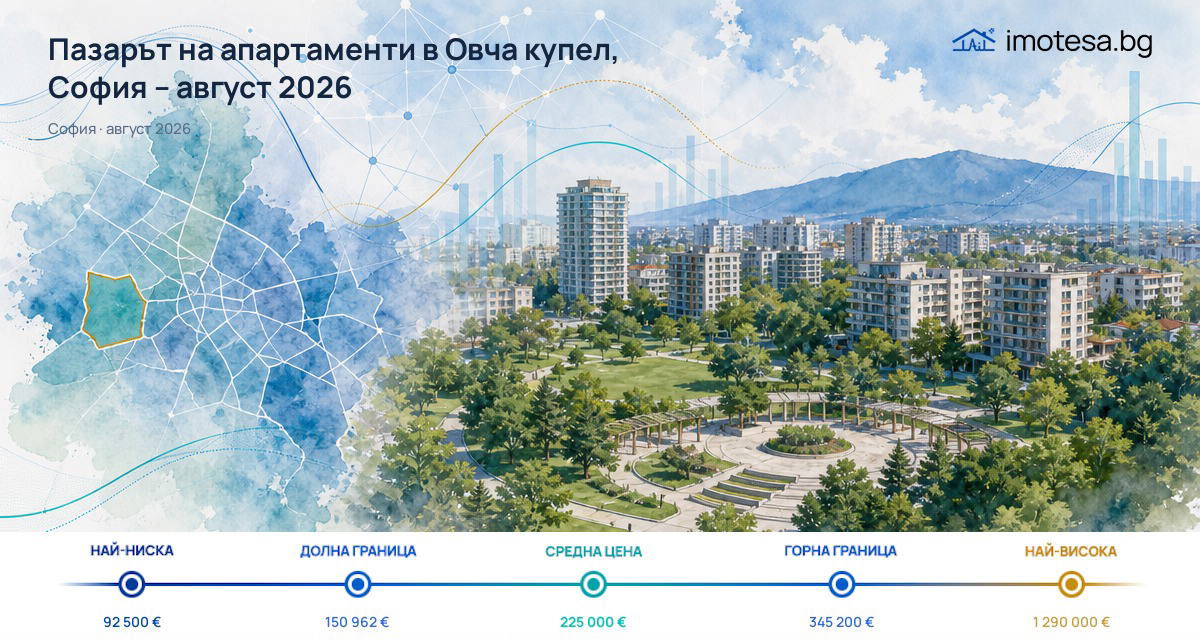
In August 2026, the typical asking price for apartments in Ovcha Kupel is €2,295/sq m and €219,300 per property. This is the value at the midpoint of the sorted asking prices (the median), not a transaction or current availability.
By price distribution, 80% of observed asking prices per square metre are between €1,912 and €2,907/sq m. In the same month, 1,189 listings and 1,042 linked properties were observed, which is a separate characteristic of supply and not a measure of sales.
Asking Prices for Sale
For sales in Ovcha Kupel, the typical asking price is €2,295/sq m, and the typical total asking value is €219,300. For the reader, this means the picture is described both per square metre and per property, but only within the listings observed in August 2026.
The range outlined by P10 and P90 is €1,912–2,907/sq m. These are not minimum and maximum values, but the boundaries of the central 80% of observations. This shows that around the typical price there is a relatively wide set of listed levels, without drawing conclusions about quality, size, or negotiating position, as such data are not provided.
Lower bound (10%)
€149,883
Median price
€219,300
Upper bound (90%)
€337,510
Active listings
1,042
Change Compared to July and May
The level of asking prices for sales in Ovcha Kupel is higher by +1.7% compared to July and also +1.7% compared to May. In absolute terms, this is €2,257/sq m in July, €2,257/sq m in May, and €2,295/sq m in August.
For Sofia as a whole, the movement is more restrained: +0.4% compared to July and 0% compared to May, with €2,580/sq m in July and €2,591/sq m in May and August. Thus, the district is moving above the city’s pace for both the one-month and three-month horizons, but this is a comparison of asking levels, not actual closed deals.
Comparison with Selected Sofia Districts
Compared to Sofia, the typical price in Ovcha Kupel is lower by €295/sq m or -11.4%. The comparison is with the city level, not the entire universe of districts, and does not provide grounds for an overall ranking.
In the selected set of Sofia districts, Ovcha Kupel is also cheaper than the following listed levels:
- Doktorski Pametnik — €5,630/sq m; the difference is -€3,335/sq m (-59.2%).
- Ivan Vazov — €4,200/sq m; the difference is -€1,905/sq m (-45.3%).
- Yavorov — €4,167/sq m; the difference is -€1,871/sq m (-44.9%).
- Izgrev — €4,104/sq m; the difference is -€1,808/sq m (-44.1%).
- Iztok — €4,000/sq m; the difference is -€1,705/sq m (-42.6%).
- Lozenets — €3,907/sq m; the difference is -€1,612/sq m (-41.3%).
These comparisons show only the selected districts and their respective typical asking prices. They do not prove geographic proximity and are not a complete ranking of Sofia, so it is correct to read them only as individual price-to-price pairs.
Asking Rents
For rentals in Ovcha Kupel, the typical monthly asking price is €642/month. This is the total monthly rent, not a price per square metre, and is also measured from the listings in August 2026.
For the rental range, P10 is €480/month and P90 is €850/month. Here too, P10 and P90 outline the central 80% of observed listed rents, without serving as minimum and maximum. Compared to July, the typical rent is down by -1.2%, and compared to May it is up by +3.6%.
Observed Listings and Linked Properties
In August, 1,189 listings for sale and 1,042 linked properties were observed in Ovcha Kupel. For rentals, the count is 506 listings and 373 linked properties. These values describe the observed supply in the monthly sample; they do not allow conclusions about deals, sales speed, or the number of new listings without additional data.
Month-on-month, the linked properties for sale in the district are -5.9% compared to July, when there were 1,107, while for Sofia the decrease is -1.3% compared to 23,698 properties. Compared to May, Ovcha Kupel is up by +5.9% with 984 properties, while Sofia is up by +8.8% with 21,503 properties. Here it is important that a higher city pace does not necessarily mean a larger absolute number of properties in every area, because different volumes and different bases are being compared.
The number of listings also includes those without a linked property, while the property count includes only the different linked properties. Due to the unknown completeness of the linking, it is not correct to draw conclusions about duplication, new publications, or market activity from the counts alone.
Summary of Supply
August 2026 shows a higher typical asking price for sales in Ovcha Kupel compared to July and May, at a level below that of Sofia as a whole and below all selected district comparisons in the set. In parallel, rents are also moving in a different direction compared to spring, and the observed counts of listings and properties suggest a change in supply without allowing conclusions about deals or causes.